Ukash Casinos in the UK: Payment Status and Alternatives
 Available in GB
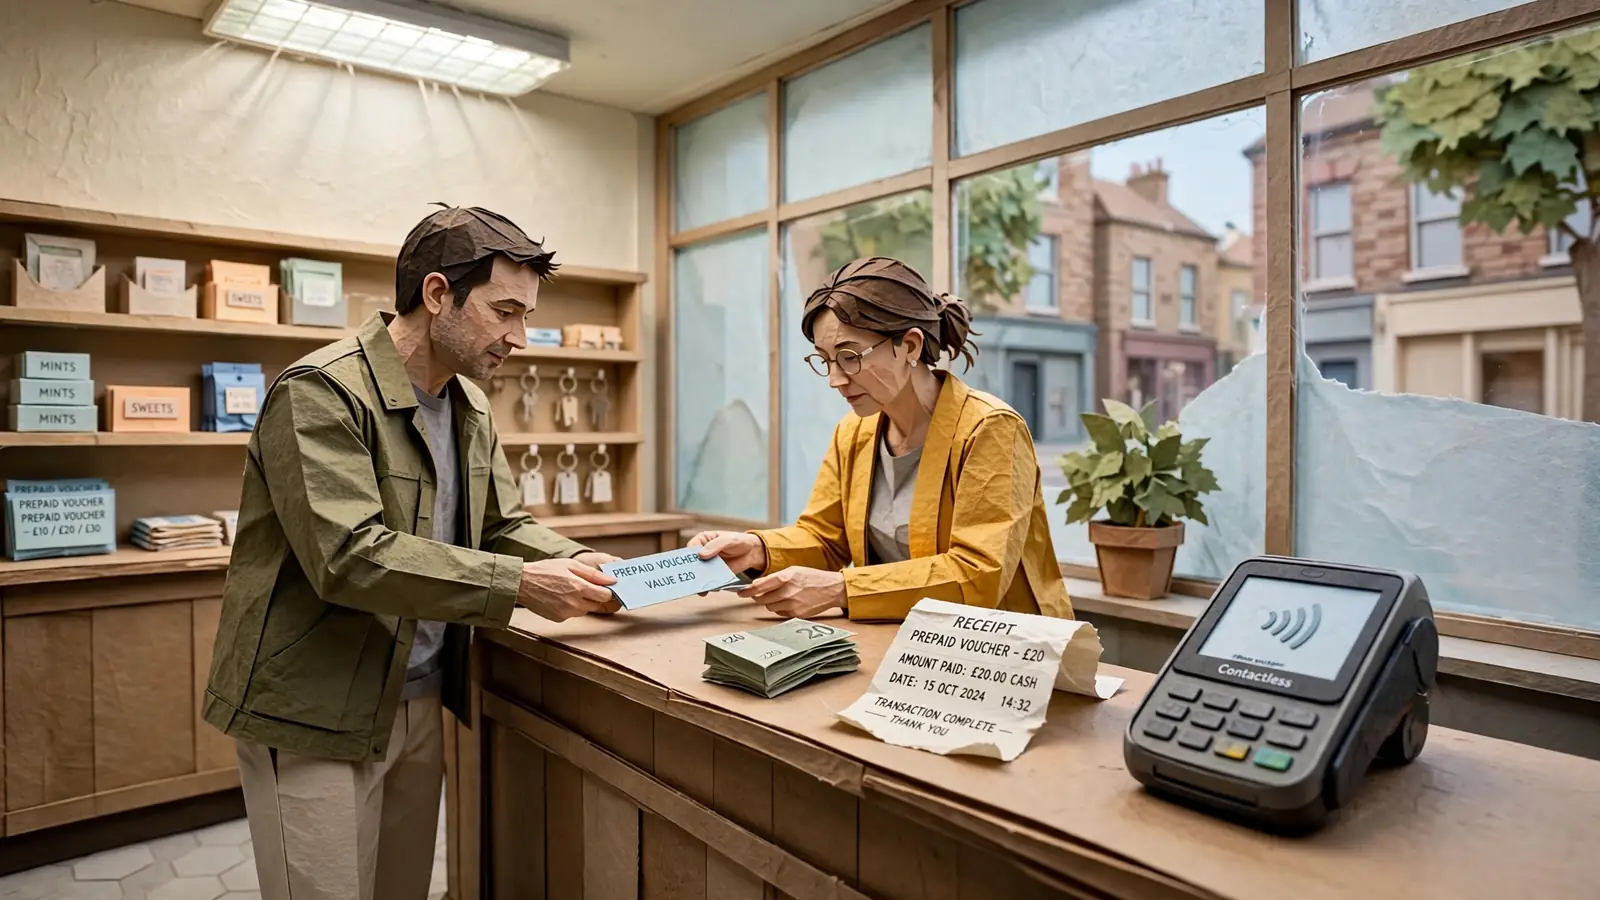
Ukash vouchers have been discontinued, while Payz is the rebranded EcoPayz service; the distinction helps clarify which payment options remain relevant.
What Happened to Ukash in the UK?
Ukash was once a familiar name in prepaid online payments. It allowed people to buy a voucher with cash and use its code for transactions on participating websites, including some gambling services. The attraction was obvious: no bank card was needed, and the payment could be separated from the holder’s main account. In an era when digital wallets were less established, that made Ukash feel like a small piece of financial independence.
That system did not remain a permanent fixture. Ukash was discontinued, so its branded vouchers are no longer a current payment route for British online gambling. The name survives because old pages, forum discussions and archived payment guides continue to circulate. A dormant brand can have a surprisingly long afterlife, particularly when it is attached to a practical question about money.
The change is also tied to the brand that followed it. EcoPayz rebranded as Payz in 2022. The new name belongs to the successor payment service, not to Ukash itself, and the distinction matters. A Payz account or payment option should not be described as a Ukash voucher simply because both belong to the history of prepaid and electronic payments.
This is why references to “Ukash casinos” can be misleading in the United Kingdom. Some pages use the expression as shorthand for a former deposit method; others preserve old information without making clear that the service has ended. The result is a familiar label attached to an arrangement that no longer exists in its original form. Digital finance is full of such ghosts: the logo disappears, while the phrase remains useful enough to keep being repeated.
The practical history is therefore straightforward. Ukash was a prepaid payment brand, it was discontinued, and its successor context is associated with Payz after the EcoPayz rebrand in 2022. Current payment information must be read carefully, because a casino page mentioning Ukash may be historical, copied or referring loosely to another service.
Casinos That Accept E-Wallets in the UK
A name can outlive a payment method.
Recommended online casinos
- BeOnBetBonus: 100% up to €500 + 100 FS · Payout speed: 1-3 business days
- NightWinBonus: £900 + 400 free spins · Payout speed: 1-3 business days
- ZombillionBonus: Welcome Pack 250% up to £4000 + 200 FS · Payout speed: 1-3 business days
- BritsinoBonus: Welcome Package – Get your £2,200 + 2,000 FS · Payout speed: 1-3 business days
- DieselwinBonus: Welcome Pack 250% up to £4000 + 200 FS · Payout speed: 1-3 business days
- Revery PlayBonus: 100% up to€1,000+ 100 FS · Payout speed: 1-3 business days
- x3betBonus: Welcome Pack 100% Up to £1.000 + 200 Free Spins · Payout speed: 1-3 business days
Are Any UK Casinos Still Accepting Ukash?
The short answer is that Ukash should not be treated as a current payment option at British online casinos in 2026. The name still appears in searches for older casino pages, payment guides and archived discussions, but that does not establish that a remote gambling licensee currently offers Ukash in its cashier.
That distinction matters. A casino can remain online after changing its payment providers, while an old article can remain visible long after its information has expired. A page mentioning Ukash is therefore not proof that a deposit made with a Ukash voucher would be accepted. The only meaningful test is the payment menu attached to the casino account at the time of the attempted transaction.
Why Ukash still appears beside casino names
Ukash belonged to an earlier generation of prepaid payment products. Its appeal was easy to understand: a customer could obtain a voucher and use its code instead of entering card details directly. That model left a durable trail across casino directories and comparison pages, where the brand became shorthand for prepaid gambling deposits.
The trail outlived the practical option. Old pages may still use phrases such as “Ukash casino”, “Ukash casinos in the UK” or “online casinos accepting Ukash” because those descriptions once matched a payment route or because the wording was never updated. A page title is not a cashier confirmation, and an old list of operators is not a current statement of availability.
There is another source of confusion. Payment brands change names, ownership or operating arrangements, while the language around them remains fixed. EcoPayz, for instance, changed its brand to Payz in 2022. That is a separate example rather than evidence that Ukash itself has returned under a new name. It does, however, show why a familiar payment label can survive after the commercial product behind it has changed. Digital finance is fond of leaving yesterday’s sign above today’s shop.
Status of Ukash Discontinued/Historical
Successor Context Payz (formerly EcoPayz)
Primary Use Case Prepaid voucher payments
What “accepting Ukash” would need to mean
For a casino to be described accurately as accepting Ukash, Ukash would need to appear as an available deposit method for the relevant British account, with the transaction supported by the casino and the payment provider. A historical mention, a third-party directory entry or a general statement that the operator accepts prepaid payments does not meet that standard.
The wording also needs care because “accepted” can conceal several different situations:
- a brand may be listed in an old payment guide but absent from the current cashier;
- a casino may display a payment logo for some countries but not for British customers;
- a provider may support deposits without supporting withdrawals;
- a payment name may refer to a successor or rebranded service rather than the original product;
- a payment page may describe a method that is temporarily unavailable or restricted to selected accounts.
These are not minor technicalities. They determine whether money can enter the gambling account, whether funds can leave it, and whether a transaction is recognised as belonging to the same customer. A logo is not a contract.
Are there UK casinos with Ukash in 2026?
That means names should not be attached to a claim that they accept Ukash unless the cashier itself confirms the method for the intended account. A list of “Ukash casinos for 2026” can look useful while quietly mixing active operators, outdated payment information and casinos that serve different markets. The reader is left with a catalogue, but not with a reliable way to fund an account.
A more precise description is therefore possible: searches for Ukash casinos continue to find historical or recycled references, but those references do not demonstrate present availability at UK casinos.
The difference between an old casino page and a live cashier
Casino payment information is account-specific. Operators may show different methods according to jurisdiction, account status, currency, risk checks or the payment provider’s current arrangement. Even a casino that once displayed Ukash could remove it without changing its name, games or wider website.
The cashier is consequently more relevant than a search result or an archived review. A live payment screen indicates what the operator is prepared to process for that account at that moment. It also reveals whether the method is intended for deposits, withdrawals or both.
Casinos That Accept Upaycard in the UK: Payment Guide · Casinos That Accept CashToCode in the UK
This is especially important because a payment route is not fully described by the word “deposit”. Some services are deposit-only, while withdrawals may have to follow a different route. UK anti-money-laundering controls generally direct casino payouts back towards the original payment source, and returning funds to that source is also a common anti-fraud measure. Where another route is proposed, extra checks may be required.
A customer should also ensure that the account information and payment details identify the same person. Consistent ownership information reduces avoidable friction over a transaction; it does not bypass KYC, source-of-funds checks or the operator’s other controls.
Why old “Ukash casino” recommendations are risky
An outdated recommendation can create several kinds of confusion at once. It may send a customer to an operator that no longer offers the stated payment method, encourage a deposit through an unrelated service, or blur the difference between a British-facing casino and a site serving another jurisdiction.
Remote gambling licensees selling into the British market must hold the relevant Gambling Commission licence, wherever the business itself is located. A casino outside that system is not a UKGC-licensed casino. The licence question is therefore separate from the payment question: a valid payment logo does not make an operator authorised, and a licensed operator is not thereby confirmed to accept Ukash.
Regulatory Warning
Credit-card payments for gambling are prohibited at UK-licensed casinos. A prepaid label should not be assumed to provide a way around these controls.
The legal setting also places practical limits around the account itself. In Britain, gambling operators must check age before allowing a customer to deposit. New customers must be prompted to set a financial limit before making the first deposit, and account-level controls must remain accessible afterwards. A payment method cannot be used to avoid those requirements.
Credit-card payments for gambling are prohibited at UK-licensed casinos, including credit-card funding routed through a money service business. Wallet payments are also restricted where the wallet permits credit-card funds to be used for gambling. A prepaid label should not be assumed to provide a way around those controls.
What should be checked before treating a method as current?
A cautious assessment of any Ukash claim depends on several separate checks:
-
The operator’s current cashier Ukash would need to be displayed as an available method for the British account, not merely mentioned in an article or footer.
-
The transaction direction The payment page should make clear whether the method is for deposits only or whether it can also receive withdrawals.
-
The customer and account details The payment account, casino account and identity information should belong to the same customer.
-
The operator’s status A casino serving Great Britain needs a current UK Gambling Commission operating licence. The licence number should be checked on the Commission’s public register before any deposit.
-
The account conditions Currency, verification requirements, transaction limits and any method-specific restrictions should be read in the cashier rather than inferred from an old review.
-
The payment route itself A service that looks like Ukash may instead be a different product, a successor brand or a merchant intermediary. The name must be identified accurately before funds are sent.
This process may appear excessive for a voucher payment. Financial systems have a talent for making small sums administratively elaborate.
Does a successor brand prove that Ukash is available?
No. The fact that EcoPayz rebranded as Payz in 2022 illustrates a change in branding, but it does not establish a relationship between Payz and Ukash, and it does not prove that a casino accepting Payz accepts Ukash. One payment brand cannot be substituted for another simply because both have been associated with digital or prepaid payments.
The same caution applies to phrases such as “Ukash alternative”. An alternative may be a different e-wallet, a voucher service or a bank-linked method. It is not Ukash, and its deposit and withdrawal rules must be checked independently. Treating a replacement as the original product turns a historical label into a false promise.
What the phrase means in 2026
When a British reader asks whether any Ukash casinos are still available, the useful answer is not a list assembled from old references. It is a distinction:
- Ukash as a historical search term: still visible in casino articles, archived pages and old discussions.
- Ukash as a currently confirmed casino payment method: not established by those references.
- A rebranded or different payment service: a separate product requiring its own confirmation.
- A live option for a British casino account: confirmed only when the current cashier offers it under the applicable account conditions.
That distinction prevents an old brand from being mistaken for a live route into a gambling account. It also keeps the payment question separate from the operator’s regulatory status, KYC process, financial-limit controls and withdrawal policy.
For 2026, “casinos that accept Ukash in the UK” is therefore best understood as a historical label rather than a dependable list of active payment arrangements. Any casino named as accepting Ukash would require direct, current confirmation in its British cashier before the claim could be treated as reliable.
Can a Prepaid Voucher Still Be Used at an Online Casino?
A prepaid voucher can still have a place in a British online casino cashier, but its role is narrower than the old idea of a universal cash substitute suggests. Paysafecard is the clearest current example: it is a prepaid voucher that can be used for deposits, while withdrawals do not follow the same route. In payment language, it is deposit-only.
Deposit-Only
Prepaid vouchers like Paysafecard often function as deposit-only methods, meaning they cannot be used to receive withdrawals from a casino account.
That distinction matters. A voucher may put funds into a gambling account without creating a matching channel for money coming back out. The deposit and the payout therefore become two separate stages, governed by different checks and procedures. What looks simple at the cashier can become less simple when a withdrawal is requested.
How a prepaid casino deposit works
A prepaid voucher is bought in advance and carries a stored value. At a casino that supports the method, the voucher details are entered in the cashier, and the selected amount is applied to the gambling balance. The casino does not receive card details at that point, which is one reason prepaid payments appeal to people who prefer not to use a bank card directly.
The method still has boundaries:
- the casino must list the voucher in its cashier;
- the voucher must be valid and have enough balance;
- the account and payment details must pass the operator’s checks;
- the voucher can fund the account, but it is not itself a withdrawal destination when the method is deposit-only.
Availability is therefore a property of the particular casino account, not of every site carrying a similar “prepaid” label. A page describing a prepaid casino deposit method cannot substitute for the cashier shown after registration and age verification.
The same principle applies on mobile. A casino may be accessible through a phone browser or mobile interface while offering a different selection of payment methods from another device or account setting. The device does not turn a voucher into a payout instrument. A mobile casino with prepaid payment still has to support the method at the account level.
What happens when the balance is withdrawn?
A deposit-only voucher cannot receive a casino payout. The operator must use another route, subject to its payment policy, ownership checks and anti-money-laundering controls. UK rules commonly require winnings to be returned to the original payment source where that is possible; a prepaid voucher makes that route unavailable for the withdrawal itself.
That does not mean a withdrawal is impossible. It means that the casino may request another payment method or bank arrangement and may carry out additional verification before releasing funds. The account holder’s name, address, identity documents and payment ownership can become relevant at this stage. A mismatched route creates avoidable friction, particularly when the original deposit was made through a voucher that cannot accept a payout.
The casino’s internal approval process also remains part of the timetable. First withdrawals can take longer while verification is completed. A prepaid deposit removes neither KYC nor the operator’s responsibility to check where funds are going.
Verification Steps
- Check the operator’s current cashier for the method
- Confirm if the method supports both deposits and withdrawals
- Ensure account and payment details belong to the same person
- Verify the casino holds a valid UK Gambling Commission licence
- Confirm the account currency matches the payment currency
This is the small administrative irony of prepaid money: it can make entry feel tidy while leaving the exit more bureaucratic.
Is Paysafecard suitable for casino use?
Paysafecard can suit a player who wants a controlled deposit amount and does not need the same instrument for withdrawal. It can also separate the gambling transaction from the details of a bank card. Those are practical features, not a promise that the route will be accepted everywhere or that it will be the least expensive option.
A specialist review may describe minimum deposits in the region of £10 to £20, depending on the payment method. That figure is not a universal prepaid-voucher rule. The amount shown at the cashier can vary with the casino, the selected method and the account’s status. A casino may also apply its own transaction restrictions, while the voucher provider can impose separate conditions.
Before treating a prepaid voucher as a suitable casino deposit, the important checks are straightforward:
- Confirm that Paysafecard appears in the casino’s live cashier.
- Check the minimum and maximum deposit values displayed for that account.
- Establish whether the account currency is GBP before confirming the transaction.
- Read the casino’s withdrawal instructions, especially where the chosen deposit method is deposit-only.
- Check whether a separate withdrawal method must be verified in the same name.
- Review any casino, provider, issuer or currency-conversion charges shown before payment.
The final point is easy to overlook. Payment costs can arise from more than a visible casino fee: the provider, bank, exchange-rate spread and network may each affect the amount received or spent. A conversion spread can be more expensive than a flat charge, so a voucher funded in one currency and used in another deserves particular care.
Prepaid vouchers and promotions
A deposit made with a voucher may be treated differently from one made by a bank card or another payment service. Bonus eligibility, contribution rules and withdrawal conditions are controlled by the casino’s terms, not by the word “prepaid” alone. A payment method can be accepted for cash deposits while being excluded from a particular promotion.
The responsible-gambling framework remains unchanged. Remote gambling operators must prompt a new customer to set a financial limit before the first deposit and provide accessible account-level controls. A prepaid balance can impose a natural spending boundary, but it is not a substitute for those controls. The account’s limits still matter, and the operator must verify age before allowing funds to be deposited.
Credit-card funding is not a workaround. UK-licensed casinos cannot accept credit-card payments for gambling, including credit-card funding routed through a money service business. A wallet is not an answer where it permits credit-card funds to be used for gambling either. The relevant question is not merely whether a voucher can be purchased, but how its value was funded and whether the payment route complies with the operator’s rules.
The practical verdict
A prepaid voucher can still be used for a casino deposit in the UK when the casino expressly supports it. Paysafecard illustrates the arrangement: useful for adding funds, but deposit-only when it comes to withdrawals. It is therefore best understood as a one-way funding tool rather than a complete payment account.
Final Verdict
Prepaid vouchers are useful one-way funding tools, but they are not a complete substitute for standard payment accounts.
For some accounts, that separation is acceptable. For others, the need to arrange a different payout route outweighs the appeal of a prepaid deposit. The cashier, the withdrawal policy, the account currency, the applicable limits and the funding source all need to fit together before the transaction is made. A prepaid voucher is not obsolete; it is simply less comprehensive than the word “payment” can imply.
What Can Replace Ukash for Casino Deposits?
A replacement for a Ukash-style deposit depends on what the old voucher was meant to provide: a separate payment balance, a familiar brand, no direct card entry, or a simple route into a casino account. Modern alternatives divide into several quite different groups. Debit cards are direct and broadly recognised; bank routes connect the casino with an account; e-wallets sit between the bank and the operator; prepaid products preserve the voucher principle but may be deposit-only.
Casinos That Accept Maestro in the UK: Payment Guide
The practical distinction matters more than the label. A payment method that accepts a deposit but cannot receive a withdrawal is not a complete substitute. Nor is a method suitable for every promotion, account, or mobile device.
Debit cards: the ordinary replacement
Visa and Mastercard debit cards are among the established deposit routes at UK casinos. They are not credit-card payments for gambling: credit cards remain prohibited for gambling transactions, including arrangements that attempt to route credit-card funding through another financial service.
A debit card offers a comparatively direct chain. Money leaves the customer’s bank account and reaches the casino through the card network. The deposit may be straightforward, but the withdrawal side can follow a different timetable. A card deposit can appear instantly while a payout takes several business days. That difference is not necessarily a payment failure; the casino may need to approve the withdrawal and complete account checks first.
Casinos That Accept USDC in the UK: What to Check · Casinos That Accept AstroPay in the UK: What to Check
The card product itself also matters. The supplied payment information identifies Visa and Mastercard as supported brands, while current availability and eligibility depend on the particular cashier and card. A card issued for a different purpose, an unsupported product, or a mismatch in account details can interrupt an otherwise familiar process.
Debit cards also sit within the casino’s financial-control framework. Remote gambling operators must ask a new customer to establish a financial limit before the first deposit and make account-level limit controls available afterwards. Payment convenience does not remove that pause for reflection. A small piece of friction, in this case, is doing useful work.
Bank transfer and open banking
Bank routes form a second broad category. Traditional bank transfer can be suitable where the account holder wants funds to move directly from a bank account rather than through a card or stored-value wallet. Open banking provides a connected version of the same idea, with the payment authorised through the banking service.
A specialist payment review describes open banking and bank transfer as routes that can offer instant deposits and rapid withdrawals at many sites. That assessment concerns the type of service, not a promise applying to every casino. The operator’s cashier determines whether a particular bank connection is supported, while the bank and the payment service can affect the movement of funds.
Bank transfer also has a less glamorous calendar attached to it. Cut-off times, weekends and currency conversion can alter when money arrives. A payment started at one point in the banking day may not behave like one started at another. Currency conversion introduces another variable where the account and casino do not use the same currency.
Debit Cards
Direct routes using Visa or Mastercard debit products.
Bank Transfer
Direct bank-account routes, including open banking options.
E-wallets
Services like PayPal, Skrill, or Neteller that sit between the bank and operator.
Mobile Pay
Device-based wallet approvals, such as Apple Pay.
The supplied pages identify GBP as supported, but the account currency still deserves confirmation before the first transaction. Avoiding an unnecessary conversion is more sensible than trying to calculate its cost afterwards.
PayPal and other e-wallets
PayPal is a prominent e-wallet alternative for casino deposits, valued in a specialist review for speed and convenience. That same kind of review notes that a PayPal deposit may fall outside a casino’s bonus eligibility. A payment route and a promotional route are therefore not always the same thing.
E-wallets can separate the casino from the bank card or bank account used to fund the wallet. That separation may be useful, but it does not turn the wallet into a loophole around gambling-payment rules. Remote operators cannot accept wallet payments where the wallet permits credit-card funds to be used for gambling. The funding path matters as much as the logo displayed in the cashier.
Skrill and Neteller are available at some UK casino sites. A specialist review also reports that these wallets are often excluded from promotions. That condition should be checked alongside the payment option rather than discovered after a deposit has already been made.
Skrill remains one of the most common deposit methods at UK-friendly casino sites in 2026, according to a specialist review. Jeton is another possibility, although a specialist review places it at only a handful of UK online casinos in 2026. It is therefore a narrower alternative rather than a general replacement for the former reach of a widely recognised voucher.
Casinos That Accept Klarna in the UK: Payment Rules · Casinos That Accept E-Checks in the UK: Payment Guide
Wallets can be especially attractive where the aim is to avoid repeatedly entering card details. They still require consistent ownership information. Using an account and a payment route belonging to the same customer reduces avoidable questions about who controls the money. The cleanest arrangement is often one named account used consistently for both deposit and withdrawal.
Apple Pay and mobile casino deposits
Apple Pay is a further route at some UKGC-licensed casinos. Its presence is relevant to mobile casino use because the payment approval takes place within a device-based wallet rather than through a paper voucher or a manually entered card number.
That does not make Apple Pay universal. Some UKGC-licensed casinos accept it for deposits, while others may not display it. The cashier remains decisive, and the payment method should be assessed for the complete deposit-and-withdrawal journey rather than for the deposit button alone.
Mobile access changes the interface, not the underlying obligations. Age must be verified before a customer is allowed to deposit, and the same financial-limit controls apply. A convenient phone payment still leads into the same account, identity and responsible-gambling framework as a desktop transaction.
Prepaid alternatives
Paysafecard is the clearest current example of a prepaid voucher route. It can be used for deposits only. That makes it closer in character to a Ukash-style payment than a bank transfer or an e-wallet, but it cannot serve as a full two-way money route where withdrawals are needed.
The deposit-only status affects how a casino account should be funded from the beginning. A payout may need to be returned through another permitted method, with additional ownership or identity checks. UK anti-money-laundering controls generally direct gambling payouts back to the original payment source, while alternative arrangements can require further verification. A voucher may therefore solve the entry point without solving the exit.
Summary of Alternatives
- Debit cards provide a direct chain from bank to casino.
- Open banking can offer instant deposits and rapid withdrawals.
- E-wallets offer convenience but may be excluded from certain bonuses.
- Apple Pay is a practical option for mobile-first users.
- Prepaid vouchers remain a niche, deposit-only alternative.
This is also why prepaid products should not be confused with no-deposit promotions. A payment method is a way to move funds; a bonus is a condition attached to an offer. The availability of one does not establish the availability of the other, and a deposit route should not be selected on the assumption that it automatically qualifies for a promotion.
Choosing between the alternatives
The most useful comparison is not simply card against wallet or bank against voucher. It is a comparison of the whole transaction:
- Debit card: a familiar route using Visa or Mastercard debit products, with a potentially immediate deposit and a separate withdrawal timetable.
- Bank transfer or open banking: a direct bank-account route that may offer instant deposits and fast withdrawals at supported sites, while remaining sensitive to banking schedules and currency conversion.
- PayPal: an e-wallet praised by a specialist review for speed and convenience, with possible bonus exclusions.
- Skrill or Neteller: available at some sites, but a specialist review reports promotional exclusions for these wallets.
- Apple Pay: accepted for deposits at some UKGC-licensed casinos and particularly relevant to device-based payments.
- Jeton: still found at a handful of UK online casinos in 2026, making it a limited rather than universal option.
- Paysafecard: a prepaid deposit method whose deposit-only character must be considered before money is sent.
Fees can arise at several points: the casino, the payment provider, the card issuer or bank, currency conversion, and the payment network may each play a part. A visible flat charge is not the whole calculation; a conversion spread can cost more than a separately displayed fee. There is no single lowest-cost method for every amount and every account, so the relevant terms are those attached to the actual transaction.
Limits differ as well. The minimum deposit may begin at £10–£20 depending on the payment method, while maximum deposits can vary by method and account status, including separate limits per transaction, day or month. Those figures are not a universal promise from one casino to another; they describe why the cashier’s terms matter before funds are committed.
Bonuses, withdrawals and consistency
Payment choice can affect more than speed. PayPal, Skrill and Neteller may be excluded from promotions according to specialist reviews. A casino bonus may therefore be available with one deposit route and unavailable with another. The same applies to offers described as no-deposit bonuses: their terms are attached to the operator and promotion, not created by the payment method itself.
Casinos That Accept Boku in the UK: What to Know
Withdrawal planning should come before deposit planning. A casino may approve a payout only after internal review, and the first withdrawal can take longer while verification is completed. A specialist review also identifies account verification and the casino’s own approval process as factors affecting withdrawal speed. Another specialist review places PayPal, open banking services and debit cards connected to fast payout systems among the quicker withdrawal routes, but that remains a comparison of payment types rather than a guarantee for every operator.
Closed-loop controls and anti-money-laundering checks explain why a casino may prefer funds to return through the original source. Where that route is unavailable, an alternative may require additional verification. Keeping the casino account details and payment account under the same customer’s name reduces one avoidable source of delay.
The legal setting is equally plain. Remote gambling licensees serving the British market need the relevant UK Gambling Commission licence, and legal online gambling in the UK is confined to licensed and regulated sites. The Gambling Act 2005 governs Great Britain, although Northern Ireland has a separate legal position. Any payment comparison therefore belongs inside the licensed market rather than beside it.
The sensible Ukash alternative is not necessarily the most modern-sounding brand. It is the route that matches the intended deposit, supports a workable withdrawal path, fits the account currency, does not quietly remove a relevant bonus, and allows the casino’s ownership and verification checks to proceed without contradiction. That may be a debit card, a bank route, an e-wallet, Apple Pay, or a prepaid deposit method. The old voucher’s simplicity survives only in fragments.
Are fast casino withdrawals guaranteed?
No. Withdrawal speed depends on the casino’s approval process and whether your account is verified; even a card deposit that is instant can take several business days to be paid out.
Why must withdrawals return to the deposit method?
Returning funds to the original payment source is a common anti-fraud and anti-money-laundering control. An alternative payout route may require extra verification.
Are Visa and Mastercard deposits definitely debit cards?
No. Visa and Mastercard are listed, but you should check the cashier to confirm that your specific card product is eligible for UK deposits.
Which payment methods are accepted in Great Britain?
UK casinos commonly accept debit cards, including Visa and Mastercard. Other methods available at some sites include PayPal, open banking, bank transfers, Paysafecard, Skrill, Neteller, Apple Pay and Jeton; check the cashier for current availability.
Which method has the lowest fees?
There is no universal lowest-fee method. Compare the casino’s charges, provider and bank fees, currency-conversion spread and any network costs for the payment and amount you plan to use.